Should You Buy a Home Now or Keep Renting?

September 23, 2026

Should You Buy a Home Now or Keep Renting?

Should You Buy a Home Now or Keep Renting?

09/23/2026

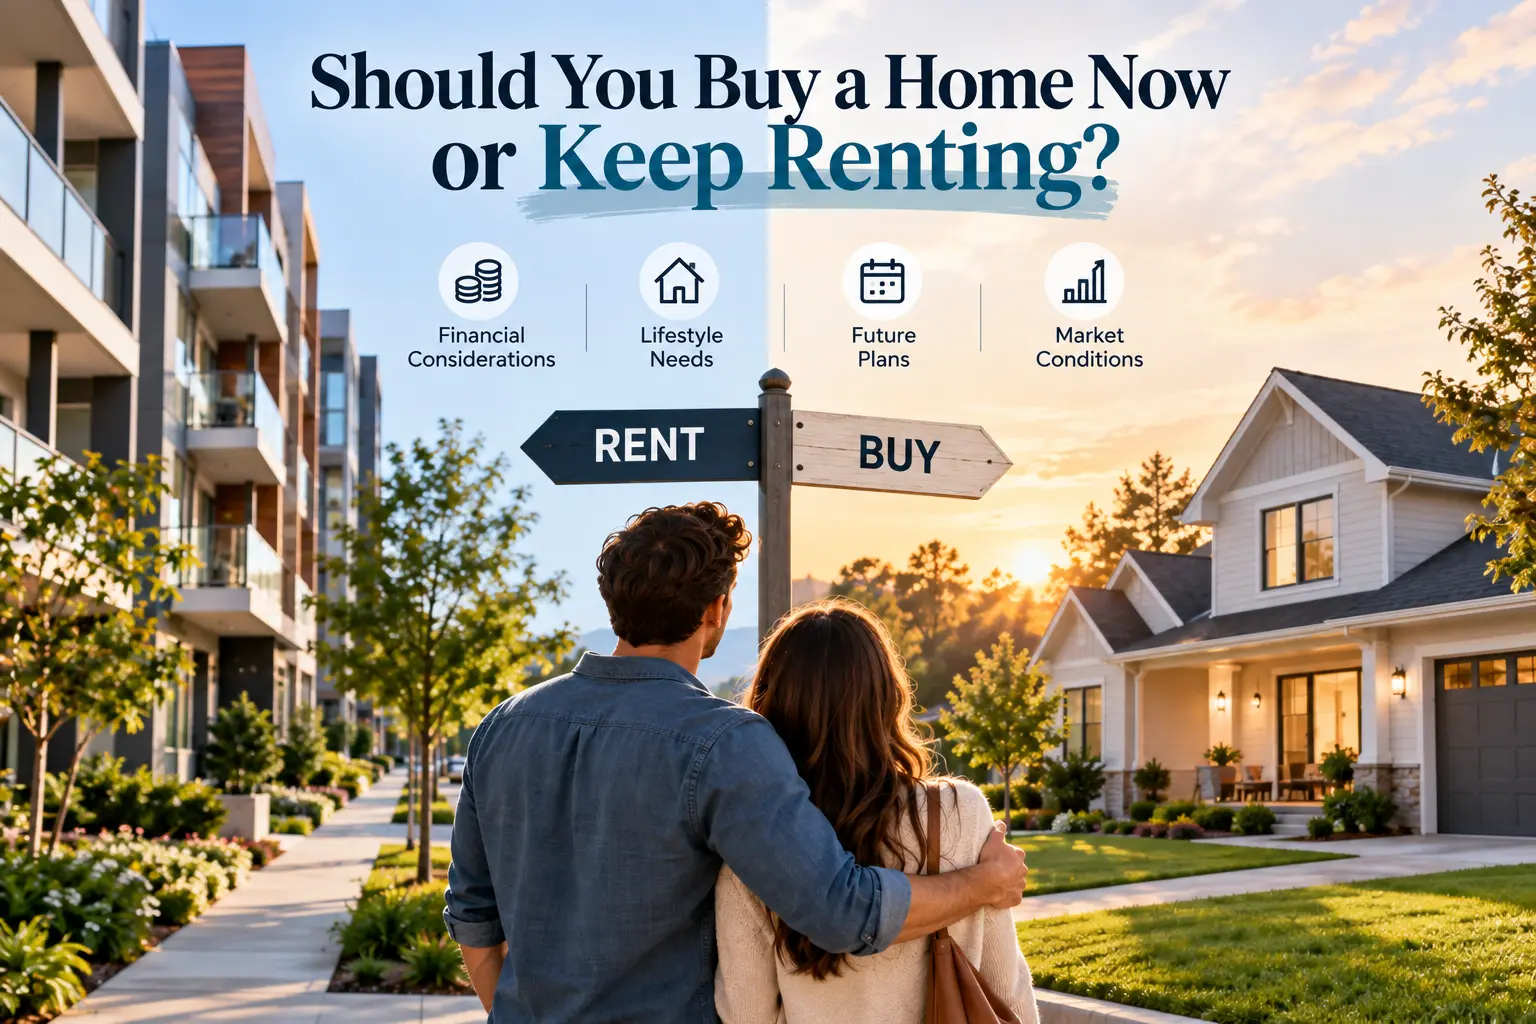
Deciding whether to buy a home or continue renting depends on more than current mortgage rates or monthly payments. The right choice should reflect your finances, lifestyle, and plans for the next several years.

Start by considering how long you expect to remain in the area. Buying usually involves upfront and future transaction costs, including inspections, closing expenses, maintenance, and eventual selling fees. If you expect to move soon, renting may provide greater flexibility.

Next, compare the complete costs of each option. A mortgage payment is only one part of homeownership. Property taxes, insurance, utilities, association fees, repairs, and routine maintenance should all be included. Renters may have fewer unexpected expenses, although rent can increase when a lease is renewed.

Your savings also matter. In addition to a down payment and closing costs, it is wise to maintain an emergency fund after purchasing. Using all your available savings to complete a purchase can leave little room for repairs or changes in income.

Homeownership may offer long-term benefits. Regular mortgage payments can build equity, and a fixed-rate loan can make the principal and interest portion of your housing payment more predictable. Owners also have greater freedom to renovate and personalize their homes.

Renting has meaningful advantages as well. It can make relocation easier, reduce maintenance responsibilities, and provide access to neighborhoods where purchasing may currently be unaffordable. For buyers still evaluating their career, family, or location plans, that flexibility may be valuable.

Market conditions should inform your decision but should not be the only factor. Waiting for the “perfect” rate or price can be difficult because no one can reliably predict short-term changes. A more practical question is whether purchasing a suitable home is affordable and supports your goals under current conditions.

Before deciding, review your income, debts, credit, savings, expected ownership period, and preferred lifestyle. A lender can help estimate financing options, while a real estate professional can provide local pricing and rental comparisons.

Buying is not always better than renting, and renting is not simply delaying ownership. Each can be the right financial and lifestyle decision depending on your circumstances. 

Comparison

Will Smith

Real Estate Advisor

📞 (815) 780-9623

httprealhub365dev.net

Florida Home Insurance Costs for Rental Properties: What Landlords Should Expect

What Should Landlords Expect From Florida Home Insurance Costs?Quick Answer: Florida home insurance costs can vary widely for landlords because carriers look at the property, the location, the age of the home, construction details, roof condition, flood exposure, rental use, and maintenance history. The most reliable number should come from current insurance estimates, policy quotes, seller disclosures, association documents, property tax records, and rental history when available. Landlords should also plan for insurance as part of the full ownership picture, not as a standalone expense. Policies and requirements may change, especially for coastal, condo, short-term rental, or older properties.Key TakeawaysInsurance costs can vary significantly by property type and location.Rental use may affect coverage options and policy requirements.Roof age, elevation, and construction details often matter.Flood coverage may be separate from standard home insurance.Association documents can reveal shared insurance obligations.Landlords should verify estimates before making an offer.One of the biggest misconceptions I hear is that insurance is just another line item landlords can estimate quickly before buying in Florida.In reality, the purchase price is only the beginning.As a local specialist serving Florida, I encourage landlords to treat insurance as part of the investment analysis from day one. Franko Agent understands that a rental property has to work on paper, but it also has to hold up to Florida’s climate, ownership rules, and changing insurance requirements.What Drives Home Insurance Costs for Florida Landlords?Several property-specific factors can affect what a landlord may pay for coverage. Insurance carriers generally evaluate risk differently depending on the home’s condition, location, construction, and intended rental use.Key items to review include:Roof age and materialWind mitigation featuresFlood zone informationProperty elevationElectrical and plumbing updatesRental occupancy typeFor landlords, the rental strategy can also matter. A long-term lease, seasonal rental, or short-term rental may create different coverage needs, and some policies may have exclusions that need to be reviewed before closing.Insurance Is Part of the Full Landlord BudgetInsurance should be reviewed alongside taxes, maintenance, association dues, utilities, reserves, and expected rental income. A property can look attractive at first glance, but the ownership costs may shift once insurance estimates and maintenance needs are added to the analysis.Accurate figures should come from current quotes and property records, not assumptions. Landlords should ask for seller disclosures, insurance claim history when available, association documents and current budget, assessment history, estoppel information, maintenance records, property tax records, and rental history.Florida’s weather also makes preventative maintenance part of protecting the investment. Salt air, humidity, strong sun, and seasonal storms can affect roofs, exterior materials, mechanical systems, and long-term upkeep depending on where the property sits.What Should Landlords Know About Condos and Associations?Condos and association-managed properties can carry shared insurance responsibilities that are separate from an individual landlord policy. The association’s master policy may cover certain common elements, while the owner may still need coverage for the interior, liability, loss of rent, personal property, and rental-specific risks.Before buying, landlords should review the association’s current budget, insurance summaries, governing documents, reserve information, assessment history, and estoppel details. Assessments and coverage obligations may change, so the latest documents matter more than past assumptions.Questions to ask include:What does the master policy cover?Are reserves currently funded?Have assessments been discussed?Are rentals restricted?What deductibles apply?Are repairs owner-paid?How Can Insurance Affect Rental Cash Flow?Insurance can affect rental cash flow because it is part of the ongoing cost of holding the property. A landlord may need to adjust expectations if coverage, deductibles, flood insurance, association obligations, or maintenance reserves are higher than originally expected.The best approach is to compare multiple current insurance estimates before finalizing the investment decision. Those estimates should match the actual rental use, property type, and location, rather than relying on a generic owner-occupied quote.No single property type automatically wins. A condo may reduce some exterior maintenance responsibilities but add association oversight, while a single-family home may offer more control but place more maintenance responsibility on the owner.Florida Landlord Insurance QuestionsDo landlords need different insurance than owner-occupants?Often, yes. A rental property may need a landlord policy or rental-specific coverage because the home is occupied differently than a primary residence.Is flood insurance included in a standard policy?Flood insurance is often separate from standard home insurance. Landlords should verify flood zone information, lender requirements, and policy options before closing.Can a short-term rental change insurance needs?Yes, short-term rental use may affect coverage options and exclusions. The policy should match how the property will actually be rented.Where should landlords get accurate insurance numbers?Current quotes from insurance professionals are the best starting point. Seller disclosures, prior policy information, maintenance records, and property documents can also help frame the risk.Do association fees include insurance?Sometimes association fees include shared insurance, but coverage varies by community and property type. Review the association documents, current budget, and master policy summary.Can older homes be harder to insure?Older homes may require closer review, especially if major systems or the roof need updates. Construction details, inspections, and maintenance records can help clarify options.What I Recommend Every Landlord Review FirstBefore closing, I encourage landlords to review:Current landlord insurance estimatesFlood insurance requirementsRoof and wind mitigation reportsSeller disclosures and claim historyAssociation insurance documentsRental rules and restrictionsMaintenance and repair recordsThese conversations are just as important as negotiating the purchase price.Is a Florida Rental Property Still Worth the Insurance Cost?For many landlords, the answer can be yes, but only when the numbers, coverage, and property condition make sense together. Insurance is not just a cost to absorb; it is part of protecting the asset and preserving the rental plan.The right property depends on your budget, timeline, maintenance comfort level, financing, rental strategy, and risk tolerance. A higher-maintenance property may still work for one landlord and not fit another.No option universally wins. The better decision is the one that gives you clear documents, current estimates, realistic reserves, and confidence about how the property will perform over time.Explore Homes for SaleBrowse Homes for SaleRelated GuidesIs Florida a Good Place to Live for Home Buyers?Is Now a Good Time to Buy a Home in Florida?Pensacola vs Destin: Where Should You Buy Your Next Florida Beach Home?Buyers GuideSellers GuideHave questions about how insurance could affect your next Florida rental property? Get in touch with Franko Agent, or explore current opportunities on httprealhub365dev.net.

Read more

What Florida Sellers Should Watch in Today’s Real Estate Market Trends

What Should Florida Sellers Watch in Today’s Real Estate Industry Trends?Quick Answer: Florida sellers should watch buyer affordability, insurance scrutiny, condition expectations, inventory shifts, and how local demand compares with national headlines. Pricing can still matter more than hype, especially when buyers are comparing your home against similar listings and total ownership costs. A strong selling strategy generally starts with current market context, clean documentation, and a realistic view of what today’s buyers may question before making an offer.Key TakeawaysLocal conditions can differ sharply from national real estate headlines.Buyer confidence often depends on affordability and total ownership costs.Insurance, maintenance, and disclosures can affect offer strength.Pricing strategy should reflect today’s comparable competition.Well-prepared homes may reduce buyer hesitation during due diligence.Documentation can help sellers answer cost and condition questions faster.One of the biggest misconceptions I hear is that a seller only needs to follow national real estate headlines to understand the market. Those headlines can be useful background, but they rarely explain how a Florida buyer evaluates one specific home, in one specific condition, at one specific moment.The current market rewards preparation more than guesswork.As a local specialist serving Florida, I look at seller strategy through the lens of buyer behavior, property condition, ownership costs, and timing. Franko Agent helps sellers think beyond the list price so the home is positioned with fewer surprises once serious buyers start asking detailed questions.What Market Trends Matter Most to Florida Sellers?The most relevant trends are the ones that affect buyer confidence before an offer is written and during the inspection period. In Florida, buyers often evaluate more than square footage and location; they may also review upkeep, insurance considerations, association rules, and future maintenance exposure.For sellers, the practical question is not whether the market is broadly good or bad. The better question is whether your home is priced, presented, and documented in a way that fits how buyers are making decisions right now.Seller strategy should account for:Competing active listingsRecent comparable salesProperty conditionInsurance questionsAssociation documentsBuyer financing sensitivityBuyer Affordability Is Shaping Seller StrategyBuyer affordability can influence how quickly a home receives attention and how firmly buyers negotiate. Even qualified buyers may be more selective when monthly ownership costs feel uncertain or when comparable homes offer clearer value.Sellers can respond by making the home easier to evaluate. That may include gathering maintenance records, reviewing seller disclosures carefully, and understanding how your property compares with similar homes currently available.The goal is not to underprice your home. The goal is to reduce friction so buyers can see the value clearly and act with more confidence.Insurance, Maintenance, and Condition Questions Carry More WeightFlorida homes often receive close review because climate, location, age, elevation, and construction can affect upkeep and insurance considerations. Salt air, humidity, sunshine, and seasonal storms can make preventative maintenance part of protecting the property’s value.Sellers should avoid guessing at costs. Accurate figures should come from current insurance estimates, property tax records, association documents, estoppel information, assessment history, maintenance records, and seller disclosures when applicable.Helpful records may include:Roof age documentationHVAC service historyWindow or shutter informationAssociation budget documentsPast assessment noticesRental history, when applicableWhat Should Sellers Know About Pricing in the Current Market?Pricing should be based on what buyers can compare today, not only on what sellers hoped the home might command. If inventory gives buyers more choices in your segment, presentation and pricing discipline may become more important.A home that enters the market with clean positioning can often create a stronger first impression than one that requires repeated adjustments. That does not mean every seller needs to be aggressive; it means the pricing conversation should be tied to current competition, property condition, and likely buyer objections.If your home has a unique feature, recent improvement, or location advantage, that should be explained clearly. If it has an upcoming maintenance need, sellers generally benefit from addressing it directly rather than waiting for buyers to discover it later.Seller Documentation Can Protect MomentumDocumentation can help a listing stay on track after buyer interest turns serious. Buyers may ask for details about association rules, reserves, assessments, rental limitations, repairs, permits, utilities, and maintenance history depending on the property type.Not every document applies to every home. Condominiums, townhomes, single-family homes, waterfront properties, and rental-used properties may carry different obligations, so sellers should confirm what applies before going live.Common review items include:Seller disclosure formsHOA or condo documentsCurrent association budgetAssessment historyProperty tax recordsRepair and service recordsWhat I Recommend Every Seller Review Before ListingBefore going active, I encourage sellers to review:Current comparable listingsRecent closed salesKnown repair itemsInsurance-related documentsAssociation obligationsDisclosure detailsShowing and timing goalsThese conversations are just as important as choosing the list price because they shape how buyers understand the home once it reaches the market.Is Selling in Today’s Florida Market Right for You?For many homeowners, the answer can be yes when the move fits your timing, equity position, lifestyle needs, and next purchase plan. A seller with a well-maintained home, clear records, and realistic pricing expectations may be better positioned than one relying only on broad market optimism.No single strategy fits every seller. The right decision depends on your property type, location, condition, carrying costs, and how much flexibility you have around timing and negotiation.If selling helps you move toward the next stage of your life with a plan that accounts for both budget and lifestyle, the current market may be worth exploring carefully. A measured strategy can help you move forward without chasing headlines.Explore Homes for SaleBrowse Homes for SaleRelated GuidesBest Florida Markets for Real Estate InvestorsIs Pensacola the Best Choice? What Panama City Beach Buyers Should Really ConsiderIs Florida a Good Place to Live for Home Buyers?Best Places to Buy on 30A in Florida Right Now: What Buyers Need to KnowPensacola vs Destin: Where Should You Buy Your Next Florida Beach Home?If you are thinking about selling in Florida, connect with Franko Agent for a measured look at pricing, preparation, and current buyer expectations. You can also explore available homes and market resources at httprealhub365dev.net.

Read more

Work with us

We Do the Work, You Live the Lifestyle

With Over 35 Years Experience and Proven Success in the 30A Real Estate Market, We are Trusted and Respected by our Clients and offer Professionalism at the Highest Standards.Our Local Knowledge Allows us to Provide the Most Honest and Accurate Information to Our Clients. Contact us today for Assistance in Locating your Property Along Scenic Hwy 30a, You won’t be disappointed.

REALHUB is on fire today

Send a message

Message successfully sent.

Reason for contacting?

I agree to receive email communication and understand I can unsubscribe at any time.

I agree to be contacted by Realhub DEV via call, email, and text for real estate services. To opt out, you can reply 'stop' at any time or reply 'help' for assistance. You can also click the unsubscribe link in the emails. Message and data rates may apply. Message frequency may vary. Privacy Policy

Sign In Sign Out

Virtual Assistant

Would you like to take the next step with this property? We can help you schedule a showing or virtual tour, or send you more details.

Yes, I would like more information.

Thank You for Your Reply, One of Our Agents will contact you as soon as possible

No, maybe later.

Thank you, you can always contact me via email, phone number or through the contact form.

Realhub AI

Lucy - Your AI-Powered Realtor

Update Your Temporary Password

Personalize your search

Enter your email and we'll notify you immediately when new listings match what you're looking for.

or enter email address

Already have an account ? Login here

Continue your home search

I agree to receive communications and understand I can unsubscribe at any time.

I agree to be contacted by Realhub DEV via call, email, and text for real estate services. To opt out, you can reply 'stop' at any time or reply 'help' for assistance. You can also click the unsubscribe link in the emails. Message and data rates may apply. Message frequency may vary. Privacy Policy

Already have an account ? Login here

We use cookies

We use cookies primarily for analytics to enhance your experience. By accepting, you agree to our use of these cookies. You can manage your preferences or learn more about our cookies policy.